Saudi Exit From mBridge Puts UAE’s Digital-Dirham Strategy to the Test
Saudi Arabia has ended active participation in mBridge, leaving the UAE with a bigger role—and greater risks—in the cross-border CBDC project.
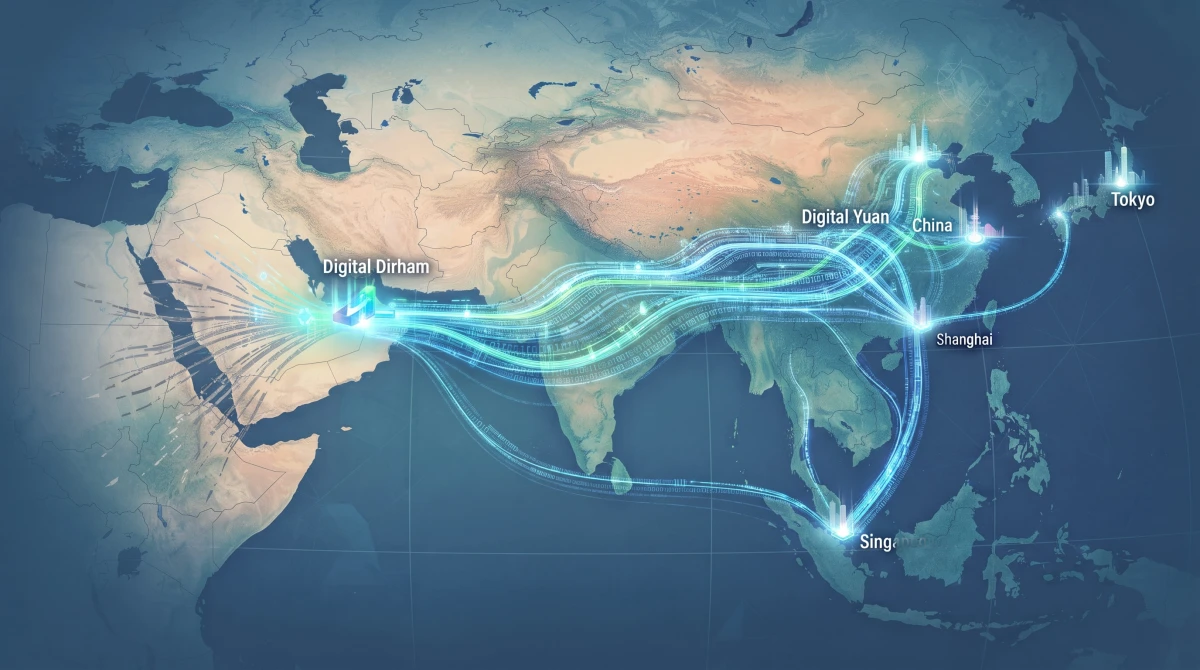
Saudi Arabia has ended active participation in the cross-border digital-currency project, leaving the UAE with a larger strategic role—and difficult questions about governance, sanctions and Chinese dominance.
Saudi Arabia has withdrawn from active participation in mBridge, the cross-border digital-currency platform developed with China, the UAE and other Asian central banks, according to the Financial Times.
The previously undisclosed withdrawal creates a strategic test for the UAE, which has treated mBridge as an important experiment in making international payments faster and less dependent on conventional correspondent-banking networks.
The Saudi Central Bank told the FT that it had completed its planned proof of concept by May 2025 and no longer participated actively in the project. Riyadh joined mBridge as a full member in June 2024, but its involvement was considerably shorter than previously understood.
Saudi Arabia’s departure does not mean the platform has closed. It does, however, reduce the breadth of Gulf participation and raise questions about whether governments are becoming more cautious about cross-border central-bank digital currencies, or CBDCs.
The Central Bank of the UAE remains listed by the Bank for International Settlements as an mBridge partner alongside the central banks and monetary authorities of China, Hong Kong and Thailand. The BIS page also continues to list Saudi Arabia, illustrating how the project’s public records have not yet caught up with the Saudi disclosure.
If Riyadh is no longer active, the UAE becomes the only GCC monetary authority still publicly associated with the project’s core group.
How mBridge was designed to work
mBridge was created to test whether several central banks could settle cross-border payments on shared digital infrastructure.
Under the model, participating central banks issue digital representations of their national currencies on a common distributed ledger. Approved commercial banks can then exchange those currencies and complete payments directly through the platform.
The structure is intended to reduce reliance on multiple correspondent banks. A conventional international payment may pass through several institutions, creating additional fees, foreign-exchange costs, compliance checks and delays.
A successful multi-CBDC platform could theoretically complete the payment and final settlement within seconds and operate outside conventional banking hours.
Earlier BIS research found that the mBridge prototype could process international transfers and foreign-exchange operations in seconds rather than days. It estimated that user costs could potentially be reduced by as much as half.
These figures were technical findings from a controlled experiment, not proof that commercial users will achieve identical savings at scale.
The project began in 2021 as a collaboration involving the BIS Innovation Hub, the CBUAE, the Bank of Thailand, the Hong Kong Monetary Authority and the Digital Currency Institute of the People’s Bank of China. It reached its minimum viable product stage in mid-2024.
Saudi departure follows the BIS exit
Saudi Arabia is not the first major institution to step back.
The BIS withdrew from mBridge in 2024, saying the platform had reached a stage at which participating central banks could continue without its direct involvement.
Then-BIS general manager Agustín Carstens rejected suggestions that the departure was politically motivated or that the system had been developed to help BRICS countries bypass sanctions. He also cautioned that mBridge was not yet mature enough for full operational deployment.
The BIS now marks the innovation project as “concluded” on its website, although activity led by the participating monetary authorities appears to have continued separately.
The FT reported that US officials have expressed concern about China using mBridge to shape international digital-payment standards or create financial channels with less exposure to the dollar and Western-controlled infrastructure.
Those concerns do not establish that transactions conducted through mBridge are designed to evade sanctions. They demonstrate why cross-border CBDC projects have become politically sensitive.
Payments technology cannot be separated completely from foreign policy. The system’s governance determines which banks can participate, what customer information is exchanged, how transactions are screened and whether sanctioned institutions can gain access.
The UAE has a stronger commercial case
The UAE has practical reasons to continue exploring cross-border digital payments.
Dubai and Abu Dhabi sit at the centre of trade corridors connecting Asia, the Middle East, Africa and Europe. UAE banks handle payments for energy, commodities, aviation, logistics, property and a large expatriate workforce.
Faster settlement could reduce the time during which companies wait for funds or remain exposed to changes in exchange rates. It could also improve cash-flow visibility for importers and exporters.
The CBUAE describes mBridge as a step towards making trade payments easier, safer and real-time. Its broader fintech strategy includes national and cross-border collaboration, digital-payment infrastructure and research into both wholesale and retail CBDCs.
The UAE has also advanced its Digital Dirham programme and previously used mBridge-related infrastructure for cross-border transactions with China.
Activity on the platform has expanded sharply. Reuters reported in January 2026 that mBridge had processed more than 4,000 cross-border transactions worth approximately $55.5 billion, based on Atlantic Council analysis.
However, about 95% of the reported value was settled in China’s digital yuan. That concentration suggests the platform’s scale is being driven mainly by China rather than evenly distributed activity across all members.
Transaction value also does not show how many independent companies use the system, how frequently UAE banks participate or how the operating costs compare with established payment channels.
Dollar dependence will not disappear
mBridge is frequently described as an alternative to dollar-based payments, but the UAE’s position is more complicated.
The dirham is pegged to the US dollar, and the UAE holds substantial commercial, financial and security relationships with the United States. Dubai’s international banking sector also depends heavily on access to dollar clearing.
Using digital dirhams to settle selected transactions with China or Thailand would not automatically weaken the currency peg or eliminate the dollar’s role in UAE finance.
The immediate benefit is more likely to be operational. A UAE company could potentially pay a Chinese supplier directly in digital dirhams and digital yuan, reducing the number of intermediaries and shortening settlement time.
The political risk emerges if the platform is perceived as a way for restricted institutions to avoid established compliance systems. UAE banks connected to the United States and Europe must continue applying sanctions screening, anti-money-laundering controls and customer due diligence regardless of the payment technology used.
A faster transaction is not necessarily a safer transaction. If settlement is immediate and final, banks may have less time to investigate errors or suspicious activity before money moves.
Governance is becoming the central question
Saudi Arabia’s departure highlights the difference between a successful technical experiment and a durable international financial network.
A prototype can demonstrate that two digital currencies move across a ledger. A production system must resolve much harder questions:
Who operates the infrastructure? Which country’s law applies when a transaction fails? How are cybersecurity incidents handled? Which authority can suspend a participant? What information is shared among central banks and commercial institutions?
The dominance of the digital yuan creates another concern. If one currency supplies nearly all transaction volume, other members could become users of infrastructure whose commercial direction and technical standards are heavily influenced by China.
The UAE can reduce that risk by demanding transparent governance, portable technology and equal influence over future rules. It should also maintain alternative payment connections rather than depending on a single CBDC network.
What happens next matters more than the exit
Saudi Arabia’s withdrawal does not invalidate the technology or end the UAE’s cross-border payment ambitions. Riyadh has said its participation was a defined proof of concept, suggesting the departure may reflect a completed experiment rather than a rejection of CBDCs.
The lack of contemporaneous disclosure is nevertheless significant. Central-bank payment systems affect banks, companies and international financial relationships, making current information about membership and governance essential.
The CBUAE had not publicly detailed its response to Saudi Arabia’s exit in the sources reviewed. It has also not disclosed recent UAE-specific transaction volumes, participating commercial banks or a timetable for broader mBridge deployment.
Those details will determine whether mBridge becomes genuine financial infrastructure or remains a strategically interesting pilot dominated by Chinese activity.
For the UAE, the project still offers a route towards quicker trade settlement and greater control over cross-border payments. Saudi Arabia’s departure shows that technological capability alone will not secure regional adoption. Trust, governance and geopolitical balance will decide whether the bridge is widely used.
Fact-check and sources
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Finance news and analysis writer with two years of experience covering markets, AI, cryptocurrency, fintech, blockchain, investment trends, and digital economy developments for global readers.

Comments (0)