Citi Brings Tokenised Deposits to the UAE’s Corporate-Payments Market
Citi has launched its blockchain-based tokenised-deposit service in the UAE, enabling institutional clients to move dollars and euros around the clock.
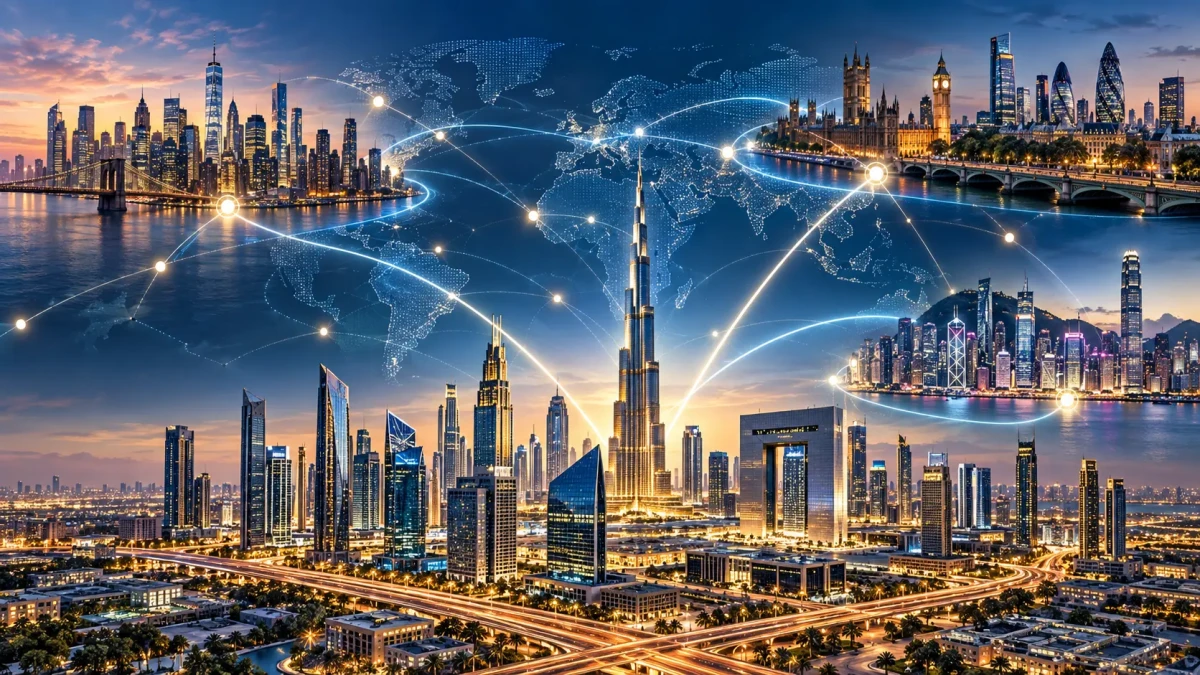
The bank’s blockchain service lets institutional clients move dollars and euros around the clock, giving the Emirates a live alternative to public stablecoins for cross-border treasury operations.
Citigroup has expanded its blockchain-based tokenised-deposit service into the United Arab Emirates, allowing corporate and financial-institution clients to transfer funds outside conventional banking cut-off times.
Citi Token Services is now live across seven markets: the UAE, United States, United Kingdom, Ireland, Singapore, Hong Kong and Japan. UAE account holders can use the system for round-the-clock transfers in US dollars and euros between supported Citi locations.
The expansion moves tokenised deposits from a controlled experiment into the UAE operations of one of the world’s largest international banks.
It also introduces a significant new choice into the country’s evolving digital-money market. Companies can use blockchain-based bank deposits without holding cryptocurrency or relying on a privately issued stablecoin.
The distinction is important. A tokenised Citi deposit remains a claim against Citi and operates within the bank’s regulated infrastructure. A stablecoin is issued under a separate legal and reserve structure and may circulate across public blockchain networks beyond the issuing institution.
For the UAE, the development connects two policy ambitions: becoming a major centre for digital assets while making cross-border trade and treasury management more efficient.
Tokenised deposits remove banking-hour restrictions
Conventional cross-border payments can be delayed by time zones, holidays, currency cut-off times and the involvement of several correspondent banks.
These delays create a practical problem for corporate treasurers.
A multinational company may receive cash in Dubai after the working day has ended in London. It may need those funds in Asia before the next UAE banking window opens. During that interval, money can remain idle even when another part of the organisation requires liquidity.
Citi Token Services converts commercial-bank deposits into digital representations on a private, permissioned blockchain. Approved clients can move those tokenised balances between participating Citi accounts at any time.
The bank’s conventional records and controls remain central to the transaction. Customers are not withdrawing money from the regulated banking system and placing it into an unregulated digital wallet.
Citi says clients in the UAE will be able to send funds to their own accounts or those of other approved clients in participating markets without being restricted by holiday calendars or traditional cut-off times.
The service could be particularly useful for companies managing operations across the Middle East, Asia, Europe and the United States.
The UAE is a natural treasury location
Dubai and Abu Dhabi host regional headquarters, commodity traders, investment companies, logistics businesses and financial institutions operating across several time zones.
Many such groups maintain centralised treasury functions in the Emirates. These teams monitor cash positions, pay suppliers, fund subsidiaries and manage currency exposures across multiple markets.
Faster internal transfers could allow a company to hold a smaller liquidity buffer in each country.
Instead of leaving surplus cash across numerous accounts for unexpected requirements, a treasurer could potentially move funds when they are needed. This may reduce idle balances and short-term borrowing costs.
The benefit will depend on how many counterparties, currencies and banking markets join the network.
A tokenised payment that moves instantly between two Citi accounts may still encounter delays when funds must leave the bank, enter a market not yet enabled or pass through a conventional foreign-exchange settlement process.
The service currently supports seven markets rather than Citi’s entire international network. Its financial value should therefore be measured using actual client transactions, liquidity savings and operating costs—not the speed of an isolated blockchain transfer.
Tokenised deposits are not stablecoins
Citi’s UAE launch arrives as stablecoins are moving closer to mainstream payments.
The bank separately expanded its partnership with Coinbase this week. Under that arrangement, Coinbase will provide infrastructure enabling Citi’s institutional merchant clients to accept stablecoin payments. Digital currency will be converted automatically into conventional money, with Citi settling the funds as bank of record.
Coinbase is also adopting Citi’s virtual-account infrastructure to provide bank-account-like functionality and automatic conversion between fiat money and stablecoins.
Those initiatives will launch first in the United States. Citi has not announced that the Coinbase merchant service is available in the UAE.
Citi Token Services is different.
Tokenised deposits represent existing money held at a commercial bank. They ordinarily cannot circulate freely among anonymous wallets or remain outside the bank’s controlled network. Stablecoins can move across blockchain platforms and may be held independently of the issuer.
For institutional users, tokenised deposits can preserve familiar protections involving bank supervision, compliance, account ownership and legal claims.
Their limitation is reach. A Citi token is most useful where both sides operate within the Citi network or a connected regulated system. A widely accepted stablecoin can theoretically move between many different platforms and service providers.
The two models may consequently coexist rather than one replacing the other.
The UAE is developing several forms of digital money
The Central Bank of the UAE is advancing the Digital Dirham while regulating private payment tokens through its Payment Token Services Regulation.
The domestic market also includes CBUAE-licensed AE Coin and the proposed DDSC dirham-backed token associated with First Abu Dhabi Bank, IHC and Sirius International Holding.
Meanwhile, UAE banks are testing blockchain infrastructure for cross-border settlement and tokenised assets.
Earlier in September, Citi worked with First Abu Dhabi Bank and Singapore’s OCBC on live transactions using Swift’s blockchain ledger. Citi said its token-services platform had already processed about $1 billion in transactions.
The combination of initiatives creates a layered digital-money system:
- Central-bank money through the Digital Dirham
- Tokenised commercial-bank deposits such as Citi Token Services
- Regulated privately issued payment tokens
- Foreign-currency stablecoins used within permitted frameworks
Each instrument has different legal protections, technical designs and financial risks.
A central-bank digital currency is a direct liability of the monetary authority. A tokenised deposit is a liability of a commercial bank. A stablecoin holder generally has a claim governed by the issuer’s reserve and redemption arrangements.
Users should not treat them as interchangeable merely because they move through blockchain infrastructure.
The business case is stronger than the crypto narrative
Citi’s launch is notable precisely because corporate clients may never need to interact with the underlying blockchain.
The useful outcome is not token ownership. It is the ability to move regulated deposits at 2am on a public holiday, automate treasury rules and reduce the time money remains trapped between accounts.
That practical focus could encourage adoption among companies that have avoided public cryptocurrencies because of price volatility, custody risks or compliance uncertainty.
Programmability is another potential advantage.
A company could eventually instruct funds to move automatically when a subsidiary’s balance falls below a defined level. Payment might be released when specified trade conditions are met, or collateral could be transferred when a financial contract requires additional security.
Automation creates new risks as well. Incorrect instructions could move funds immediately, while compromised credentials or defective smart-contract logic could operate outside normal business hours.
Banks therefore need strong limits, authentication, monitoring and reversal procedures. Always-on payments require always-on risk management and customer support.
Interoperability will determine the outcome
Private bank-led networks can become fragmented if each institution builds an incompatible system.
A company may receive an instant tokenised deposit at Citi but still need to convert it before paying a supplier using another bank’s network. If that process requires manual intervention, some of the promised efficiency disappears.
Citi’s work with Swift, FAB and OCBC is therefore as important as the underlying token technology. Shared messaging and settlement standards could allow different banks’ platforms to communicate without forcing every participant onto one private ledger.
Regulators must also determine how tokenised deposits interact with liquidity requirements, deposit protections, sanctions screening and cross-border data rules.
The UAE is well placed to test these questions because it combines large international trade flows, a sophisticated banking sector and several active digital-money initiatives.
Citi’s launch does not mean blockchain has replaced conventional corporate banking. It demonstrates that the technology is being embedded inside it.
The next measure of success will be commercial evidence: transaction volumes, participating companies, supported corridors and documented reductions in settlement time or liquidity costs.
If those figures prove meaningful, the UAE could become an important bridge between traditional bank deposits and the always-on financial infrastructure that global businesses increasingly expect.
sources
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Finance news and analysis writer with two years of experience covering markets, AI, cryptocurrency, fintech, blockchain, investment trends, and digital economy developments for global readers.

Comments (0)